Self-employed, fixed-term, just back from abroad? Your file can be built.
Banks do not refuse a profile, they refuse a file they cannot read. We put yours in the order they expect, with the documents that answer their questions.
What we usually ask the self-employed for
- The last three balance sheets and tax returns
- The current year's figures, even provisional
- Personal and business bank statements
- Your contracts, orders or order book
The list changes with your status: we send you yours after the first meeting.
What we finance
Your first home, alone or as a couple: what you can borrow, the zero-rate loan if you are eligible, and a file that reassures the bank.
First-time buyers, alone or as a couple
€1,500, paid at the notary only if the loan is granted
Buy the next home before selling the current one: the bridging loan explained, with what happens if the sale takes longer.
Owners who buy before selling
€2,000, paid at the notary only if the loan is granted

A flat to rent out: the loan, the rental income the bank takes into account, and the impact on your borrowing capacity.
Investors, first rental or further one
1% of the loan, minimum €1,500, paid at the notary

Your loan is running: we check whether renegotiating it with your bank, or moving it to another one, is worth the costs.
Owners with a loan already running
€1,200, paid only if the operation is carried out
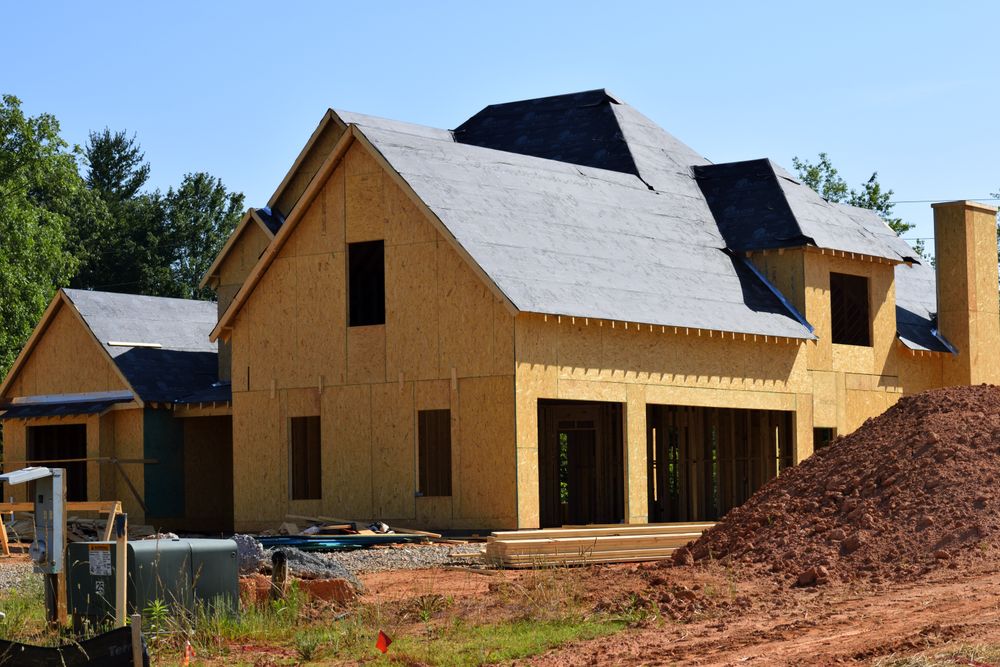
A plot and a house built by a builder: funds released step by step, in line with the stages of the work.
Households building their home
€1,800, paid at the notary only if the loan is granted
The insurance of your loan can be chosen freely and changed at any time: we compare it with the bank's.
Every borrower, new loan or running one
Study free of charge
What frames our work
Registered with ORIAS
Our registration number appears on every page and can be checked on orias.fr. It is what allows us to present your file to banks.
A written mandate, fees stated
Before we approach any bank, you sign a search mandate that states our fees in euros. No surprise at the notary's.
Nothing to pay before the loan
The law forbids any payment before the loan is obtained. If no bank says yes, you owe us nothing.
Your loan insurance, your choice
You are free to choose the insurance of your loan, and to change it at any time afterwards. We compare it with the bank's.
Ten days to think
The loan offer cannot be accepted before ten full days. We go through it with you, line by line, before you sign.
No rate promised
We compare and negotiate; the bank decides. Nobody can honestly promise you a rate or a date before your file has been studied.
Real situations, described without names. Every file is different: these are not promises.
| Recent files | ||
|---|---|---|
First purchase as a couple Couple, one on probation, Angers | File presented with the employer's letter confirming the end of probation and twelve months of regular savings. | Loan granted over 25 years, zero-rate loan included |
Self-employed buyer Craftsman, 3 years of balance sheets, Saumur | Two banks had refused directly. File rebuilt around the last three balance sheets and the order book. | Loan granted after the third bank |
Buy before selling Retired couple, Cholet | House found before the flat was sold. Bridging loan sized on 70% of the agent's valuation. | Bridging loan over 12 months, repaid after 5 |
Renegotiation Owner, loan taken in 2023, Angers | Calculation of penalties and fees against the remaining interest, then renegotiation with the same bank. | Lower monthly payment, same duration |
Second rental flat Employee, one loan running, Nantes | Rent estimate from an agent, existing loan presented with its remaining duration. | Loan granted with a 10% deposit |
Change of loan insurance Couple, loan of 2021, Tours | Equivalent cover found with another insurer, change request accepted by the bank. | Insurance changed during the loan |
From the first meeting to the notary
The first meeting
Free, at the agency or by video: your project, your income, your savings, and what you could borrow.
The file and the mandate
We list the documents to gather, check them with you and sign the mandate that states our fees.
The banks
We present your file to several banks and negotiate the rate, the insurance, the fees and the flexibility clauses.
The offer
We compare the proposals with you, then the bank issues its offer. Ten days of reflection before accepting.
The notary
The funds are released at the signing. Our fees are due only then.
"Self-employed for three years, two banks had said no on their own. The broker rebuilt the file around my balance sheets."
"Our first purchase, with a small deposit and one of us still on probation. They told us which documents would reassure the bank, and they were right."
"We had to buy before selling. The bridging loan was explained clearly, with what would happen if the sale took longer."
Ask for your free study
Tell us about the project, the amount and your deposit. We call you back to set the first meeting, at the agency or by video.
Rather talk now? 01 23 45 67 89
